The Investment Journal

Independent Research · Long-Term Plays

The stock market got its Halloween scare a bit early this year.

On Oct. 30, Intel told investors the rest of the year would be weaker than they’d hoped, and by the closing bell, its shares had tanked nearly 30%.

Amazon slid after its own disappointing report, and Dell followed it down.

But the selling didn’t stop with the companies that delivered bad news.

For weeks, investors had been quietly wondering whether the hundreds of billions of dollars pouring into AI would ever pay for themselves.

That day, a lot of them decided they’d rather not wait around for the answer, so they sold almost anything whose value rested on a big promise about tomorrow.

Yet another corner of the market seemed to be having a completely different week…

Big Pharma Handed Out the Treats

Eli Lilly gave investors an early treat on Oct. 29, climbing more than 6% to a record close while the broader market slipped.

The next day, as Intel was having one of the worst days in its history, AstraZeneca jumped about 7%.

So right before trick-or-treat, with the whole market on edge, two of the world’s biggest drugmakers were heading the other way.

What did they have that Intel didn’t?

Both beat Wall Street’s expectations for the quarter, but Lilly went a step further.

It told investors it now expects to bring in about $5.5 billion more this year than it forecast just a few months ago, which is more than plenty of well-known public companies make in an entire year.

Almost all of that comes from two drugs people are lining up for right now: Mounjaro and Zepbound.

Nobody Skips Their Medicine Over a Bad Report

When you buy into the AI boom, you’re buying a vision.

It may pay off enormously, but much of the money being spent today won’t show up as profit for years, and nobody knows exactly how much of it ever will.

When markets are calm, investors are happy to wait for that payoff, but once nerves kick in, waiting suddenly feels a lot riskier.

A weight-loss drug doesn’t ask anyone to wait.

Patients are filling prescriptions this month, doctors are writing more of them next month, and the revenue is already landing.

People don’t skip their medication because a chipmaker had a bad quarter or the market had a rough week.

That kind of steadiness rarely makes headlines when everything’s rising, but when the market turns jittery, it’s exactly where a lot of investors want their money.

What Drug Giants Do With All That Cash

Companies like Lilly and AstraZeneca can’t afford to sit on their profits, because every blockbuster drug eventually loses its patent protection.

When that happens, cheaper copies flood in, and billions in yearly sales can start disappearing almost overnight.

So the big drugmakers are always hunting for whatever comes next, and more and more often, they find it by buying it.

They let smaller biotech companies take on the early, risky work of discovering and testing new treatments, then write a very large check once the science starts to look promising.

Merck paid about $10 billion for Verona Pharma after its lung treatment reached the market, and Pfizer paid roughly $14 billion for Medivation and its prostate cancer franchise.

Now imagine what happens when those same buyers are raising their forecasts and watching their share prices climb — they get even more firepower to go shopping.

That doesn’t mean every small biotech is about to be bought out, since most experimental drugs never make it to market.

But when the industry’s biggest buyers are flush with cash, the companies with something worth buying tend to get a lot more attention.

Before You Pile Into Pharma

None of this means tech is finished or that drug stocks only go up.

One strong quarter doesn’t guarantee another, and Lilly’s shares were already expensive heading into the week.

A company that leans this heavily on a couple of products carries its own kind of risk, especially with competitors racing to launch weight-loss drugs of their own and pricing pressure from Washington still hanging over the industry.

And if the next round of tech earnings calms fears about AI spending, some of that money could flow right back where it came from.

Still, that week was a useful reminder. When markets get jumpy, investors stop asking how big a company could become and start asking what it’s earning today.

The next few weeks should show whether that week’s move was a one-off flinch or the start of something bigger.

Either way, it’s worth watching where the money goes when the market gets scared.

Silver investors have had quite a ride in 2026…

The precious metal started the year with an explosive rally that carried prices above $120 an ounce, an almost unimaginable figure just a few years ago.

Then came the inevitable correction…

By mid-October, silver had surrendered more than half its value, trading around $57 an ounce and leaving plenty of investors wondering whether the great silver bull market had already come and gone.

But there’s something interesting happening beneath the surface of that selloff.

Silver mining companies are generating extraordinary profits. 

Some are reporting record cash flows, expanding margins, and strengthening balance sheets even as the metal they produce trades for less than half its January peak.

And looking ahead to 2027, some of Wall Street’s biggest banks see silver climbing back toward $75 an ounce while others see $80. 

And the possibility of another run toward $100 hasn’t disappeared entirely.

That’s setting up a potentially lucrative opportunity for investors willing to look past the volatility and focus on something that ultimately matters more than silver’s daily price fluctuations.

Earnings.

Wall Street Sees a Big Silver Rebound in 2027

It’s easy to get discouraged when an investment loses half its value in less than a year.

But perspective matters…

Silver’s January peak reflected an extraordinary combination of investment demand, geopolitical anxiety, supply constraints, and speculative enthusiasm.

But the fact that prices couldn’t hold those levels doesn’t mean the bull market’s underlying fundamentals have disappeared.

Consider what Wall Street’s commodity analysts are projecting…

UBS’ forecast has silver reaching $75 an ounce in the first half of 2027. Bank of America also projects $75, but during the second and third quarters.

ING has forecast an average price of $79 throughout 2027, while Commerzbank has called for $80 by year-end.

And Bank of America has suggested that another rally above $100 is possible, although its analysts have warned that such prices might prove unsustainable once again.

These aren’t small moves…

With silver recently trading around $57 an ounce, a recovery to $75 would represent a gain of roughly 32%. And at $80, we’re talking about a 40% advance.

Another run to $100 would mean an increase of approximately 75%.

And while those are big numbers for the metal itself…

They’re nothing compared to what could happen to the profits of companies pulling that metal out of the ground.

Silver’s Supply Problem Isn’t Going Away

The fact is that the world continues to consume more silver than it produces.

According to the Silver Institute, 2026 is expected to mark the sixth consecutive year of a global silver market deficit, with a projected shortfall of approximately 67 million ounces.

And silver is a particularly interesting commodity because it plays two very different roles in the global economy.

It’s a precious metal that investors purchase as a store of value, much like gold.

But it’s also an indispensable industrial material used in electronics, electrical infrastructure, automobiles, telecommunications equipment, and countless other applications.

The expansion of artificial intelligence infrastructure and data centers creates another growing market for silver-intensive electrical equipment.

Meanwhile, opening a new mine can take a decade or longer…

Permitting, financing, construction, and infrastructure development don’t happen simply because commodity prices suddenly become attractive.

That means established producers have a particularly valuable advantage.

They can sell silver into today’s market without waiting years to bring new projects online.

And they’re already collecting the rewards…

The Incredible Profit-Multiplying Power of Silver Miners

Here’s something a lot of investors don’t fully appreciate about mining companies.

When silver prices rise, miners’ profits can increase much faster than the price of the metal itself.

That’s because mining companies have significant operating costs that don’t necessarily rise in proportion to silver prices.

Consider a hypothetical mine producing 10 million ounces annually at an all-in sustaining cost of $30 per ounce.

At $50 silver, that mine generates a simplified operating margin of $20 per ounce, or $200 million annually.

Now imagine silver rises to $80 an ounce…

Suddenly, the mine’s margin jumps to $50 per ounce, or $500 million annually.

Silver prices increased 60%. But the mine’s operating margin increased 150%.

And if silver reaches $100?

That same operation could generate $700 million in annual operating margin, assuming costs and production remain constant.

That’s 250% more than it generated with silver at $50.

And that’s the magic of operating leverage.

It’s why mining stocks can deliver returns that dramatically exceed the gains in the commodities they produce.

Now, of course, leverage works in both directions. Falling silver prices compress margins, particularly at higher-cost mines.

But for efficient producers, a sustained recovery toward $80 could create an extraordinary opportunity.

The Record Profits Are Already Rolling In

We don’t need hypothetical examples to see what higher silver prices are doing for mining companies.

Just look at First Majestic Silver…

During the second quarter of 2026, the company reported $415.5 million in revenue, up 57% from the previous year.

But its mine operating earnings didn’t increase 57%; they jumped 353%, from $49.4 million to $223.6 million.

Meanwhile, free cash flow surged 150% to $194.6 million.

That’s precisely the operating leverage we’re talking about.

And First Majestic isn’t alone…

Pan American Silver generated approximately $344 million in attributable free cash flow during the second quarter, while returning a record $300 million to shareholders.

Now, those second-quarter results benefited from silver prices higher than today’s levels, so the next earnings reports will be important…

But if silver recovers toward $75 or $80 in 2027, companies with controlled costs and steady production will enjoy another round of massive profit growth.

Share Prices Follow Earnings

There’s an old saying on Wall Street that the stock market is a voting machine in the short term but a weighing machine in the long term.

And what that means is that investors vote with their emotions every day.

Fear, enthusiasm, geopolitical headlines, and commodity-price swings determine what they’re willing to pay for a stock.

But over longer periods, the market weighs the underlying financial performance of the business.

And that’s the opportunity I’m watching in silver miners heading into 2027…

These companies are already generating substantial profits and cash flows with silver trading well below January’s peak.

If prices recover toward $80, earnings could grow considerably faster than the metal itself.

And if silver makes another run toward $100, the upside for efficient producers could become extraordinary.

Now, that doesn’t mean every mining stock is a bargain. Production costs, debt, political risks, and valuations still matter.

But while everyone else is wondering whether silver can return to $120, I’m asking a different question.

What happens to the share prices of already-profitable silver miners if silver merely reaches $80 and stays there?

The answer could be one of the most compelling investment opportunities of 2027.

And investors who recognize it before the next wave of earnings growth shows up on Wall Street’s radar could have a major advantage.

After acquiring a slice of 800MHz radio spectrum, SpaceX’s ambitious goal is clear.

Most people view SpaceX as a “rocket company” but financially and strategically, Starlink makes them a global satellite internet service provider.

In its first earnings report as a public company, SpaceX posted $7.8 billion in second-quarter revenue — up 92% from a year ago — and Starlink alone operates across 160 markets, with over 12 million active customers.

The company already agreed to spend $19.6 billion to acquire 65 MHz of wireless spectrum license from EchoStar to expand Starlink’s direct-to-cell and mobile services.

Earlier this month, SpaceX bought a slice of 800 MHz radio spectrum from Grain Management, which could potentially eliminate the need to partner with AT&T, T-Mobile, or Verizon.

After announcing this major development, the “Big Three” stocks crashed over 7%.

This could not only reshape the US telecom industry entirely, but every company that can put satellites into orbit could stand to benefit tremendously.

And Bezos isn’t sitting still …

A Massive “Satellite Arms Race” Between Two Mega-Telecom Networks

In order to offer high-speed internet nationwide, both Amazon and SpaceX need to have as many satellites up there as possible.

Amazon Leo (Bezos’s own telecom network) has deployed nearly 400 satellites so far, but compared to Starlink’s whopping 11,000+ active satellites, Leo has some serious catching up to do if it wants to stay in the race.

After Elon Musk’s announcement, Jeff Bezos-backed ventures are actively planning and deploying thousands of new satellites to rival SpaceX’s network.

Where The Real Opportunity Lies

As SpaceX pushes its Starlink Mobile Network and Amazon Leo scrambles to get more satellites in orbit, global launch capacity is quickly becoming one of the most valuable bottlenecks in technology.

SpaceX is well positioned on its end, building its own rockets to launch more and more Starlink satellites each week. But Amazon doesn’t have that luxury, and it has even bought from its biggest rival just to keep Leo in the game.

As the trend grows, companies like Rocket Lab — already the world’s second most active launch provider — could catch the overflow. Its Neutron rocket is designed specifically for deploying satellite mega-constellations.

The more satellites this race demands, the more rides to orbit it’s going to need.

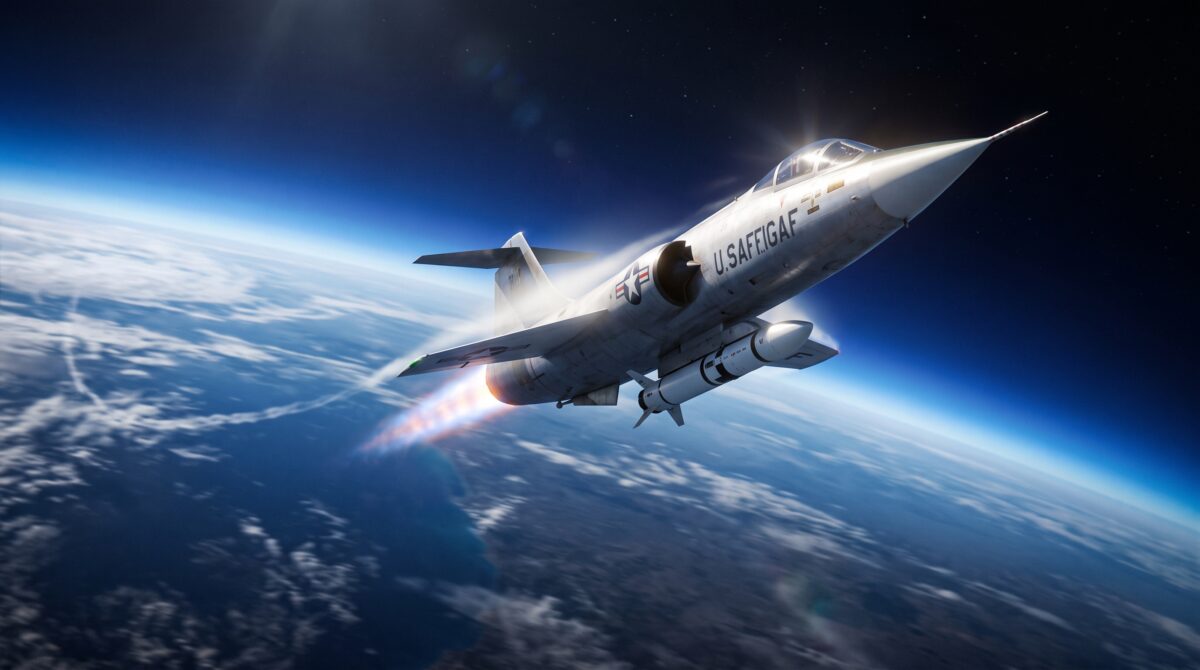
On September 13, 1985, Air Force Major Wilbert “Doug” Pearson climbed into the cockpit of an F-15A Eagle at Edwards Air Force Base in California.

His mission was unlike anything the military had attempted before…

His target wasn’t another aircraft. It wasn’t a missile or an enemy installation.

It was a satellite orbiting hundreds of miles above Earth.

Pearson accelerated his fighter jet, pulled into a steep climb, and released a 2,600-pound missile. 

The weapon streaked toward space, where its miniature homing vehicle slammed into the Solwind P78-1 satellite at approximately 15,000 miles per hour.

The satellite was American, not Soviet. 

But the test was designed to demonstrate that the United States could destroy an orbiting spacecraft in response to the Soviet Union’s growing anti-satellite capabilities.

It also demonstrated something considerably more interesting…

An ordinary fighter jet could serve as the launch platform for a vehicle capable of reaching space. 

Forty-one years later, that demonstration is taking on renewed significance…

And one little-known American aerospace company could help turn it into an entirely new military capability.

The Space Race That Never Quite Took Off

The F-15’s successful intercept was supposed to be the beginning of something much bigger.

Instead, political opposition and budget constraints eventually killed the program.

The technology, however, didn’t disappear…

In 1990, Orbital Sciences launched its Pegasus rocket from a B-52 bomber, successfully placing a satellite into orbit using an airborne launch system.

Pegasus eventually completed 45 launches, delivering more than 90 satellites into orbit.

And other programs followed…

DARPA launched its Airborne Launch Assist Space Access program, or ALASA, in 2011. 

The goal was to launch small satellites within 24 hours for less than $1 million per mission.

But problems with its experimental rocket propellant led to the program’s cancellation in 2015.

Virgin Orbit subsequently developed LauncherOne, successfully placing satellites into orbit using a modified Boeing 747.

Unfortunately, technical failures and financial difficulties eventually drove the company into bankruptcy.

Pegasus survived, but its limited launch activity and aging aircraft left America without a robust airborne-launch industry. 

But now, the military is taking another look. And this time, the stakes are much higher.

Why America Needs Fighter Jets That Launch Satellites

In August 2026, Air University Press published a research paper titled Reigniting a National Airborne Space Launch Capability.

Written by Air Force Lieutenant Colonel Ali Hamidani, the paper argues that America needs to revive airborne launch to protect its increasingly vulnerable satellite infrastructure.

And the reasoning is straightforward…

Modern warfare depends on satellites for communications, navigation, surveillance, missile detection, and countless other capabilities.

But Russia and China have spent decades developing weapons capable of disabling or destroying those satellites.

In 2007, China destroyed one of its own weather satellites using a ground-launched missile.

Russia conducted a similar test in 2021, creating more than 1,500 pieces of trackable orbital debris.

Both countries have also demonstrated technologies capable of maneuvering near other spacecraft. 

And I’m sure you can imagine what happens if a future conflict begins with the destruction of several critical American satellites…

The military would suddenly lose access to essential communications, intelligence, and navigation capabilities.

And replacing those satellites could become a matter of national security.

But conventional satellite launches depend on a relatively small number of fixed installations.

Those facilities are expensive, geographically constrained, and potentially vulnerable to attack.

However, an aircraft-based system offers another option…

Instead of waiting for an available launchpad, the military could deploy an aircraft to a suitable operating location, carry a rocket high into the atmosphere, and release it toward orbit.

That flexibility could allow replacement satellites to reach space more quickly while making the launch infrastructure itself harder to target.

Lt. Col. Hamidani argues that America should develop this capability before a conflict makes it urgently necessary.

He proposes using the Air Force Test Pilot School and Space Test Fundamentals program at Edwards Air Force Base to develop the technology through incremental flight-testing projects. 

But here’s where the story gets especially interesting for investors…

A small American company is already working on precisely this kind of technology.

Starfighters Space Is Already Building the Solution

Starfighters Space (NYSE American: FJET) isn’t your typical aerospace startup…

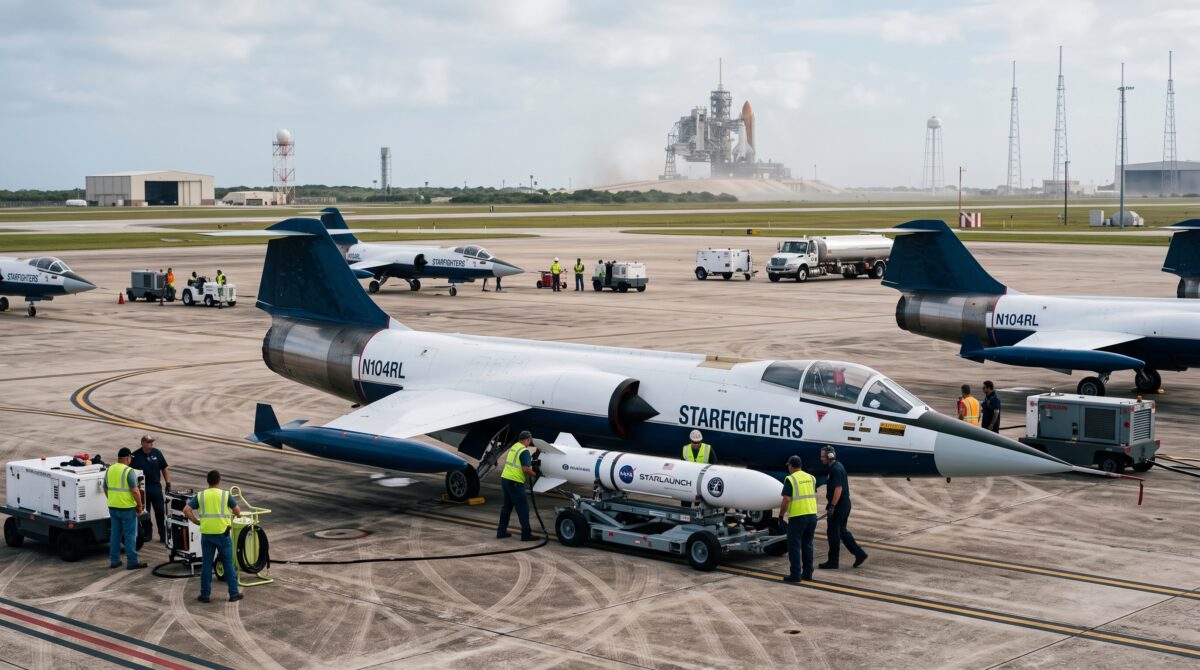
Rather than spending billions developing an entirely new aircraft, the company operates a fleet of seven F-104 Starfighters.

These legendary Cold War fighter jets can exceed Mach 2 and carry payloads to approximately 45,000 feet.

Operating from NASA’s Kennedy Space Center, Starfighters uses its aircraft for aerospace research, flight testing, and the development of airborne launch capabilities.

Its STARLAUNCH program is designed to eventually use the F-104 as a reusable launch platform for small satellites.

And the company has already made progress toward that goal…

In January, Starfighters completed wind tunnel testing that demonstrated clean separation of its STARLAUNCH 1 vehicle from an aircraft platform at both subsonic and supersonic speeds.

The company subsequently advanced the vehicle’s critical design review with support from GE Aerospace.

It has also established relationships with aerospace companies developing propulsion systems, hypersonic technologies, and launch infrastructure.

These include partnerships with Blackstar Orbital, Integrated Launch Solutions, and Vaya Defense & Space. 

Now, Starfighters hasn’t yet demonstrated an orbital launch… 

Its initial STARLAUNCH vehicle is being developed for suborbital missions, with orbital launch representing a subsequent objective.

But the company already possesses something many aspiring launch providers lack:

Operational supersonic aircraft, experienced flight crews, existing infrastructure, and an established aerospace testing business.

That combination could make Starfighters a valuable partner as the military works to develop the airborne-launch capability Lt. Col. Hamidani describes.

And there’s an interesting historical connection…

The Lt. Col.’s paper specifically notes that the Air Force Test Pilot School once operated rocket-equipped F-104 Starfighters capable of climbing above 100,000 feet.

The same aircraft family Starfighters Space is using today. 

The Military Opportunity Wall Street Could Be Missing

Perhaps the most important observation in the paper concerns the economics of airborne launch…

Previous programs demonstrated that the technology works.

But what they couldn’t consistently demonstrate was that the commercial market could sustain it.

Traditional rockets have become increasingly affordable, making it difficult for specialized airborne systems to compete on price alone.

But national security requirements are different…

When the military needs to replace a critical satellite immediately, the cheapest launch isn’t necessarily the most useful.

And Lt. Col. Hamidani argues that the government should financially support airborne launch as a strategic capability rather than depending entirely on commercial demand. 

That could be a pretty big deal for Starfighters…

A sustained military commitment to airborne launch could create opportunities for aircraft operators, propulsion developers, testing companies, and eventually orbital launch providers.

And Starfighters’ existing aircraft and flight-testing experience could position it to participate in that development.

Of course, the company hasn’t been selected for the program proposed in the paper, and future military contracts aren’t guaranteed. 

But the opportunity is becoming increasingly clear…

Forty-one years ago, an American fighter jet demonstrated that an aircraft could launch a weapon into space.

Today, the military is examining how that same basic concept could help protect America’s satellite infrastructure.

And Starfighters Space is already developing the technology that could help make it happen.

SpaceX solved one of the biggest problems in the history of the space industry.

It made getting to orbit dramatically cheaper.

Reusable rockets transformed launch economics and helped turn space from something accessible primarily to governments into a legitimate commercial market. 

And the results are becoming impossible to ignore…

Satellites now support communications, navigation, weather forecasting, agriculture, finance, national security, Earth observation, and a growing list of commercial services. 

More countries and companies are putting hardware into orbit than ever before. Yet launch capacity remains remarkably concentrated. 

In fact, in 2025, the United States accounted for 55% of global launches and an astounding 87% of objects launched, largely because of SpaceX. 

That’s an incredible accomplishment. But it also exposes the next bottleneck…

The future of the space economy can’t depend entirely on giant rockets lifting giant batches of cargo according to predetermined launch schedules.

Eventually, space transportation needs to start looking a lot more like transportation here on Earth.

And that’s where Starfighters Space (NYSE American: FJET) gets interesting.

Space Needs More Than a Highway

We’ve compared today’s space economy to the early internet before.

The internet created a new transportation network for data. Once that network existed, entrepreneurs built businesses on top of it that nobody could have imagined beforehand.

The same thing is beginning to happen in space.

SpaceX has essentially built the interstate highway to orbit. But an economy can’t run on interstate highways alone.

You need feeder roads, delivery trucks, warehouses, specialized transportation, and ways to move smaller loads exactly where and when they’re needed.

And that infrastructure is still being built.

The federal government clearly recognizes the problem.

The U.S. Department of Transportation recently created a new SPACE Task Force as part of an effort to dramatically increase commercial launch activity, with a stated objective of reaching 10,000 annual launches by 2035. 

And you don’t go from a couple hundred annual launches to 10,000 by simply making today’s rockets slightly faster.

You need entirely new approaches, and Starfighters is developing one of them.

A Fighter Jet with a Second Career

Starfighters operates what it describes as the world’s only commercial fleet of flight-ready Mach 2+ supersonic aircraft.

They’re F-104 Starfighters — legendary Cold War-era fighter jets originally designed to go extraordinarily fast and high.

But the investment opportunity isn’t based on nostalgia. It’s based on what those aircraft can do today.

Instead of firing a rocket from the ground, Starfighters’ STARLAUNCH concept would carry a small rocket underneath an F-104, climb to altitude at supersonic speed, and launch from the air.

That changes the equation…

Traditional rockets require launchpads, range availability, favorable weather, and tightly controlled launch windows. 

But air launch provides considerably more flexibility.

An aircraft can take off from a runway, maneuver around weather, travel toward a desired launch location, and give a small payload a significant head start before the rocket engine even fires.

For customers that don’t need to send an enormous satellite into orbit, that flexibility could be enormously valuable.

And while STARLAUNCH remains under development, Starfighters has been building commercial applications for its fleet right now.

The Business Is Moving Faster Than the Stock

That’s one reason the recent weakness in FJET shares has caught our attention.

The stock has fallen considerably since we first covered it. But the company hasn’t spent 2026 standing still.

Starfighters entered the year having demonstrated its platform through three supersonic captive-carry flights supporting GE Aerospace’s ATLAS program. 

It has since continued developing what it calls its “Wind Tunnel in the Sky” — essentially using actual Mach 2+ flight to test hardware in conditions that ground-based simulations can’t perfectly reproduce.

That’s becoming increasingly important as America races to develop hypersonic weapons, defenses, spacecraft, propulsion systems, and other high-speed technologies.

In March, Starfighters partnered with Blackstar Orbital to integrate and eventually flight-test Blackstar’s reusable hypersonic SpaceDrone using Starfighters’ F-104 platform. 

The company has also partnered with Mu-G Technologies around microgravity research, joined a Kennedy Space Center consortium focused on space manufacturing and research, and engaged Integrated Launch Solutions to help advance STARLAUNCH.

Then Starfighters started bringing in people with firsthand experience building modern launch systems.

In May, it recruited two former Blue Origin leaders who worked on the New Glenn program to help accelerate STARLAUNCH development and flight operations. 

That same month, Starfighters secured a $17.5 million strategic investment intended to fund STARLAUNCH development, infrastructure, and commercial expansion. 

More Pieces Keep Falling into Place

Earlier this month, Starfighters announced an MOU with The Bionetics Corporation covering preparation, integration, testing, and data retrieval for small payloads flown aboard its F-104s.

It sounds mundane compared with launching rockets.

But payload processing is exactly the kind of infrastructure a commercial space transportation network needs.

A rocket isn’t very useful if customers don’t have an efficient system for getting hardware prepared, integrated, flown, recovered, and analyzed. 

Then came another agreement.

Starfighters and Vaya Defense & Space announced plans to evaluate Vaya’s Vortex-Hybrid rocket engine for STARLAUNCH while also exploring the use of Starfighters aircraft to carry Vaya hypersonic test articles.

That agreement effectively touches both sides of the company’s strategy: 

Earn money providing high-speed flight-testing services today while developing the launch system that could create a considerably larger opportunity tomorrow. 

That’s the model we’re watching.

Don’t Think About Starfighters as Another SpaceX

This is where investors can easily misunderstand the opportunity…

Starfighters doesn’t need to beat SpaceX and it probably shouldn’t even try.

SpaceX is exceptionally good at moving tremendous amounts of cargo into orbit.

The opportunity for Starfighters is to solve a different problem…

Imagine FedEx trying to compete with an ocean-going container ship.

That would be ridiculous.

The container ship wins on bulk freight. But FedEx wins when something small has to be somewhere quickly.

A mature space economy will need both…

It will need giant reusable rockets carrying thousands of kilograms at once.

But it will also need specialized missions, rapid testing, responsive launch, small-payload delivery, microgravity research, hypersonic development, and transportation options that aren’t entirely dependent upon somebody else’s launch schedule.

The bigger the space economy becomes, the bigger that secondary transportation ecosystem becomes with it.

And we’re already seeing capital pour into companies trying to fill those niches. 

In fact, investor interest in defense and space companies has surged this year as governments increase spending on launch, hypersonics, drones, satellites, and other emerging technologies. 

Buying the Turbulence Before Takeoff

None of this eliminates the risks.

Starfighters remains a speculative company.

STARLAUNCH still has to be successfully developed and demonstrated. MOUs need to turn into contracts. Contracts need to turn into revenue. 

And the company will have to prove that its unique fleet can support a sustainable commercial business rather than simply an interesting collection of aerospace projects.

That’s a lot of execution still ahead.

But speculative investing is rarely about waiting until all the uncertainty disappears.

By then, so does much of the opportunity.

What matters to us is whether the underlying story is progressing.

And Starfighters has made substantial progress throughout 2026…

It’s adding partners. It’s adding experienced aerospace personnel. It’s developing payload infrastructure. It’s generating real-world experience with hypersonic testing. It’s advancing STARLAUNCH.

And it’s doing all of this while one of the largest new industries on the planet is beginning to encounter exactly the transportation and infrastructure problems Starfighters was created to address.

The stock has hit turbulence, but the space economy hasn’t.

And if Starfighters can turn the pieces it’s assembling today into a functioning commercial platform, investors may eventually look back at this weakness as the period when the opportunity was easiest to overlook.

America just threw almost everything it could at Golden Dome and Golden Dome shot it all down.

That’s the good news. But the less good news is what we didn’t throw at it…

Hypersonic missiles.

Those may ultimately be among the most dangerous weapons Golden Dome will ever be asked to defeat.

And right now, America has a problem…

Because before you can build a defense against a new weapon, you have to be able to test that defense.

Over and over again.

Under realistic conditions.

And when it comes to hypersonics, America simply hasn’t been able to do that nearly often enough.

That’s created what the Pentagon’s own Defense Innovation Unit calls a “national bottleneck” in hypersonic development.

And one tiny aerospace company is helping GE Aerospace break it wide open.

Golden Dome Just Proved It Can Fight

A few weeks ago, the Pentagon put real pieces of the emerging Golden Dome architecture through an integrated missile-defense test.

And this wasn’t supposed to be an easy demonstration…

Golden Dome program manager Gen. Michael Guetlein emphasized that the military is deliberately pushing the system toward failure.

It’s trying to discover where sensors, software, interceptors, and command systems break before an enemy gets the opportunity to find out for us.

Yet the latest exercise delivered a remarkable result:

“We shot down everything that we put in the air in a matter of 34 minutes,” Guetlein said.

The Pentagon hasn’t disclosed exactly what targets were used or which interceptors destroyed them.

But the point of the exercise was bigger than any single missile.

Golden Dome isn’t one weapon.

It’s supposed to be a gigantic network tying together satellites, radars, sensors, command systems, and multiple kinds of interceptors into one integrated shield.

And the latest testing indicates that important pieces of that architecture can already work together.

That’s a huge step forward.

But it’s only a step.

Because the threats Golden Dome is ultimately supposed to defeat include something far harder…

Hypersonic weapons.

The Missile That Doesn’t Play by the Old Rules

Traditional ballistic missiles are incredibly fast but they’re also comparatively predictable.

Once detected and tracked, their trajectory can be modeled. Missile-defense systems can calculate where the warhead is going and try to put an interceptor in its path.

Hypersonic weapons change that equation…

They can travel at more than five times the speed of sound while maneuvering through the atmosphere.

That combination of speed and maneuverability dramatically compresses reaction times and makes predicting their path much more difficult.

China and Russia have poured enormous resources into these systems.

And Golden Dome is explicitly being designed with maneuvering hypersonic weapons among the threats it eventually needs to counter.

There’s just one major problem:

If we want to learn how to shoot down hypersonic weapons, we need realistic hypersonic targets to shoot at.

And those are extraordinarily difficult and expensive to produce.

The Pentagon has dozens of hypersonic programs underway, but the Defense Innovation Unit says progress has been constrained by a shortage of affordable, reusable, high-cadence testing platforms.

Think about that…

You can design the best radar in the world.

You can develop a revolutionary interceptor.

You can create advanced algorithms capable of predicting the movements of a maneuvering missile.

But eventually you have to leave the computer simulation behind.

You have to put hardware in the sky.

And you have to do it again.

And again.

And again.

That testing bottleneck is exactly what the Pentagon’s HyCAT program — Hypersonic and High-Cadence Airborne Testing Capabilities — was created to solve.

And last week, that program took another major step forward.

GE Aerospace Just Got the Call

On September 1, GE Aerospace announced that the Defense Innovation Unit had awarded it a new contract to advance development of a hypersonic test bed under HyCAT.

GE will develop a liquid-fueled system consisting of a booster and hypersonic cruiser that can be combined into a complete test vehicle.

The goal is relatively simple to explain: Give the military a more flexible way to repeatedly put hypersonic systems into realistic flight conditions.

That could allow engineers to test propulsion, materials, guidance, sensors, communications…

And eventually technologies designed to track and defeat hypersonic weapons.

Now, GE is one of the biggest aerospace companies on Earth.

But buried deeper inside this story is a company that’s a tiny fraction of its size.

Starfighters Space (NYSE American: FJET).

And it’s been working on this problem for years.

A Mach 2 Laboratory in the Sky

Starfighters owns and operates a fleet of F-104 Starfighter aircraft.

These jets were originally designed during the Cold War to intercept Soviet ICBMs.

But today, Starfighters is using them for something completely different…

Research, testing, and eventually, air launch.

You see, the F-104 can sustain roughly Mach 2 flight and carry experimental equipment into real supersonic conditions.

That effectively turns the aircraft into a flying laboratory.

And GE Aerospace has already used it…

Starfighters previously joined the HyCAT effort as a subcontractor working with Innoveering, which GE Aerospace acquired a few years ago.

Then, as part of GE’s Atmospheric Test of Launched Air-breathing System program, Starfighters flew an advanced propulsion test vehicle aboard one of its F-104s during three successful supersonic captive-carry flights.

That matters because hypersonic development doesn’t begin at Mach 5…

Before a new engine, sensor, material, or vehicle ever reaches hypersonic speeds, engineers need to understand how it behaves during acceleration, at altitude, in extreme airflow, and under real aerodynamic stresses.

Starfighters provides a relatively inexpensive way to gather that data in the actual atmosphere rather than relying entirely on a wind tunnel or simulation.

And now that GE is advancing the next phase of the HyCAT program, the opportunity could become much bigger.

You Can’t Build a Shield Without Something to Shoot At

This is the part investors shouldn’t overlook…

The hypersonic arms race isn’t simply a competition to build the fastest missile.

It’s creating an entire supporting industry.

America needs better propulsion systems, better heat-resistant materials, better sensors, better guidance, better tracking, better interceptors, and an enormous amount of testing.

The Pentagon says its existing test infrastructure is one of the biggest obstacles standing in the way.

And that makes companies capable of increasing testing cadence strategically important.

Because ultimately, Golden Dome’s effectiveness against hypersonic threats won’t be determined by a PowerPoint presentation.

It’ll be determined in the sky…

We’ll have to launch realistic threats, track them, predict their movements, and destroy them.

Then we’ll need to make the test harder and do it again.

That’s how missile defenses mature.

And that’s why the latest Golden Dome success may actually make the hypersonic testing problem even more important.

We just demonstrated that large pieces of America’s future missile shield can work together against the threats we can currently test.

Now we have to prepare it for the threats that are much harder to reproduce.

GE Aerospace is helping build that capability.

And quietly flying alongside one of the largest aerospace companies on Earth is tiny Starfighters Space.

Sometimes the biggest defense programs create opportunities in unexpected places.

Golden Dome could become one of the largest military technology projects America has attempted in decades.

But before its most advanced interceptors can defend the country from hypersonic missiles, someone has to help give America the ability to test them.

And Starfighters may have found itself directly in the middle of that mission.

SpaceX dominates the global launch business and nobody else is even close…

Its reusable Falcon 9 rockets transformed the economics of getting to orbit, dramatically lowering costs while increasing launch frequency. 

And SpaceX now sends more payload into space than the national programs of most major countries combined.

And that’s because it solved one of the biggest problems holding back the space economy:

Cost.

But it hasn’t solved another one…

Time.

And that could create a huge opportunity for a much smaller company (and for investors who get in early)…

Cheap Doesn’t Always Mean Fast

SpaceX has made space launch cheaper and more routine than ever. But sending something into orbit is still nothing like booking a flight…

Customers often have to reserve space well in advance, deliver payloads weeks before launch, wait for the right mission, and hope weather, range availability, technical issues, and orbital requirements all cooperate.

And SpaceX’s rideshare program perfectly illustrates the problem…

It offers remarkably affordable access to orbit. 

But its sun-synchronous rideshare missions generally launch about once every four months. 

And customers typically have to deliver payloads to the launch site roughly 30 days ahead of liftoff.

For many companies, that’s fine. But for others, it could be a deal-breaker…

Imagine operating equipment in orbit and needing a replacement component quickly.

Or running a microgravity experiment tied to a narrow biological window.

Or being a defense agency that suddenly needs another sensor overhead.

Those customers may not care about saving another 10% or 20% on launch costs.

They may care far more about whether they can launch this week instead of next quarter.

And that’s the next problem the space economy needs to solve…

Space Needs Air Freight

It helps if you think about SpaceX as the container ship of space…

Container ships are incredibly efficient because they move enormous amounts of cargo cheaply.

But we still have airplanes. Why?

Because sometimes speed matters more than scale.

FedEx doesn’t compete with container ships by carrying more cargo. It solves a different problem…

It gets smaller packages where they need to go quickly.

The space economy will eventually need the same thing.

And that’s where a little known firm called Starfighters Space (NYSE American: FJET) gets very interesting…

Don’t Call Them Missiles

You see, Starfighters operates a commercial fleet of F-104 Starfighter aircraft capable of sustained Mach 2+ flight.

And its STARLAUNCH system is designed to use those aircraft as the first stage of a space launch…

Instead of firing a massive rocket from sea level, an F-104 carries a smaller projectile to roughly 45,000 feet before releasing it.

The rocket then ignites and continues toward space.

And that changes the launch equation….

The aircraft is reusable.

It can take off from a runway.

It can move to a favorable launch location.

It begins above a significant portion of the atmosphere.

And, most importantly, it could potentially give customers much more control over when they launch.

You see, Starfighters isn’t trying to replace Falcon 9…

It’s trying to make small-payload launches more responsive.

And that distinction could be enormously valuable…

From Months to Hours

Because the eventual goal is something closer to on-demand access to space…

Instead of waiting months for an available rideshare mission, a customer could theoretically schedule a launch much more like an aircraft operation.

And that would reduce one of the last major friction points standing between companies and space…

Because cheaper transportation doesn’t just make existing businesses more profitable.

It creates businesses that couldn’t exist before.

Railroads did it. Highways did it. Commercial aviation did it. The internet did it…

Once people could move goods, people, or information faster and more reliably, entrepreneurs invented entirely new industries around that capability.

And there’s no reason to think that space won’t follow the same pattern.

Imagine companies manufacturing high-value materials in orbit…

Pharmaceutical researchers running constant microgravity experiments…

Satellite operators replacing failed hardware rapidly…

Defense agencies deploying equipment on short notice…

Space stations receiving urgent supplies…

Many of those businesses become far more attractive if reaching orbit takes days instead of months.

Starfighters Is Still Early

This is important…

STARLAUNCH isn’t yet a mature orbital transportation system.

Starfighters is still developing and testing the technology.

But the company has completed wind-tunnel testing for STARLAUNCH I and raised additional capital to advance development, flight operations, infrastructure, and launch readiness.

STARLAUNCH I is initially aimed at suborbital and microgravity missions. And STARLAUNCH II is intended to take payloads into orbit.

And that means FJET remains highly speculative…

The company will need more testing, regulatory approvals, capital, and successful demonstrations before anyone can say the system works commercially.

But that uncertainty is also why the opportunity exists…

If Starfighters had already proven reliable on-demand launch capabilities, the market would value the company very differently.

What Happens If It Works?

This is where things get particularly interesting…

Starfighters doesn’t necessarily have to beat SpaceX. It could simply complement it.

SpaceX could remain the dominant provider of heavy, high-volume transportation.

And Starfighters could serve smaller, urgent, specialized missions where responsiveness matters more than sheer capacity.

And if STARLAUNCH proves that capability, larger aerospace companies are likely to become very interested…

That could mean partnerships. It could mean strategic investment. And yes, eventually it could even mean an acquisition.

SpaceX has acquired complementary space technology before, including satellite company Swarm Technologies.

And now, we should be clear: there is absolutely no evidence that SpaceX plans to buy Starfighters today.

But that is not the investment thesis…

The more important point is that a proven rapid-launch capability could become strategically valuable to any major player trying to dominate the future space economy.

The Missing Piece

SpaceX already changed the world by making launch cheaper. But the next breakthrough may come from making it easier…

Faster…

More flexible…

More available…

More like transportation and less like a major engineering event.

And if STARLAUNCH can shrink the timeline from months to days, or even hours, Starfighters could remove one of the biggest remaining barriers to commercial activity in space.

And once transportation becomes cheap and responsive, the space economy could accelerate much faster than most investors expect.

SpaceX built the highway…

Now, Starfighters is building the express lane.

And if it succeeds, this tiny company could become a very valuable piece of the next phase of the space boom.

Every great economic expansion has eventually run into the same problem: Transportation.

It doesn’t matter how valuable the resources are, how good the products are, or how revolutionary the technology is…

If you can’t move things where they need to go quickly, reliably, and cheaply, the opportunity stays limited.

But eventually somebody solves the transportation problem, and everything changes.

That’s essentially what happened when railroads spread across America in the 1800s… 

Before them, distance placed a hard limit on economic growth. 

A farmer might have valuable crops, a miner might find valuable ore, or a manufacturer might have customers hundreds of miles away.

But none of that mattered much if getting goods to market took weeks and cost a fortune.

Then railroads changed the equation…

The first transcontinental railroad was completed in 1869. 

And by 1893, five transcontinental lines and thousands of miles of connecting track had helped create something that barely existed before: a truly national economy. 

Factories could suddenly sell products thousands of miles away. Farmers could reach distant markets. Entire towns, industries, and supply chains grew alongside the tracks.

Because the railroad wasn’t simply another industry…

It was the infrastructure that allowed countless other industries to exist at a scale that had been impossible without them.

And we’ve seen the same thing happen again and again…

Build the Road and the Economy Follows

The automobile provided transportation freedom that railroads couldn’t. But the automobile alone wasn’t enough…

America needed roads.

As roads improved, trucking became practical. Suburbs expanded…

Motels, gas stations, roadside restaurants, shopping centers, logistics companies, tourism businesses, and thousands of other industries grew around a transportation system that suddenly allowed people and products to travel farther and faster.

And the Federal-Aid Highway Act of 1956 accelerated that transformation by building the modern Interstate Highway System.

There’s a great line from Thomas MacDonald, the longtime head of the Bureau of Public Roads, that sums it up:

America didn’t build its highways because it was rich. Its highways helped make America rich.

Once again, transportation infrastructure created economic opportunity.

But that was far from the last time or the most recent example…

Soon, another transportation network that worked differently but followed the same economic pattern emerged and changed the world again…

It was called the internet.

Instead of transporting people or physical goods, it transported information.

And suddenly, information that once required letters, telephone calls, libraries, couriers, newspapers, or physical documents could move almost anywhere on Earth virtually instantaneously.

And look what grew on top of that network…

E-commerce, cloud computing, streaming video, social media, online banking, remote work, software-as-a-service, digital advertising, smartphones, artificial intelligence, and countless businesses that would have sounded ridiculous before the underlying network existed.

Amazon couldn’t exist at its current scale without the internet. Neither could Google. Nor could Netflix. Or the modern cloud computing industry.

But nobody laying fiber-optic cable in the 1990s needed to predict TikTok to understand that making information dramatically cheaper and easier to move would create enormous economic opportunities.

And that’s the lesson investors should remember today.

Because another transportation revolution is getting underway. Only this road goes straight up…

Space Has a Transportation Problem

The space economy already exists…

In fact, the Space Foundation calculated that it reached $613 billion in 2024, with commercial activity accounting for 78% of the total. 

And McKinsey and the World Economic Forum estimate it could reach $1.8 trillion by 2035.

But there’s still one enormous constraint: getting there.

Because for most of human history, putting something into orbit has been an extraordinarily expensive, slow, complicated undertaking.

Rockets were built largely by hand. Most major components were used once and thrown away. 

Launches required enormous amounts of planning. And customers often had to design their schedules around the rocket rather than the other way around.

Imagine trying to build the modern American economy if every truck cost tens of millions of dollars, was destroyed after making one delivery, and required months of preparation before leaving the warehouse.

Well, that’s essentially the transportation system the space industry inherited. But companies are finally replacing it…

Building the Railroad to Orbit

SpaceX demonstrated the biggest breakthrough by making rocket reuse routine.

As of March 31, 2026, Falcon 9 boosters had flown as many as 34 times, according to company filings. 

And SpaceX says its next-generation Starship system is being designed around full and rapid reusability, pushing the industry toward something much closer to an actual transportation network than the expendable rockets of the past.

But SpaceX isn’t alone…

Rocket Lab has already launched Electron more than 90 times and is developing the larger Neutron rocket around a reusable first stage. 

It now has more than 70 missions on its manifest, demonstrating just how quickly demand for reliable access to orbit is growing.

And similar efforts are underway across the industry…

Companies are developing reusable rockets, air-launch systems, mobile launch infrastructure, orbital transfer vehicles, space tugs, refueling technology, and other systems designed to make getting payloads into space, and moving them once they’re there, faster, cheaper, and more routine.

That’s the important part…

We’re not simply building better rockets. We’re building transportation infrastructure for space.

And history tells us what happens next…

What Happens When the Toll Falls?

When transportation costs collapse, businesses that previously made no economic sense suddenly become viable.

Cheap rail transport made it profitable to develop resources hundreds or thousands of miles from customers.

Highways turned distant farmland into suburbs and created entirely new categories of commerce.

The internet reduced the cost of distributing information nearly to zero and produced trillion-dollar industries nobody had imagined beforehand.

Lower launch costs will do something similar…

More satellites become economical. Replacing them more frequently becomes practical.

Building enormous communications constellations becomes possible.

So does more sophisticated Earth observation, space-based manufacturing, private space stations, tourism, orbital servicing, debris removal, lunar infrastructure, asteroid exploration, space-based computing, and eventually industries we don’t even have names for yet.

And, honestly, that last category may ultimately be the biggest…

McKinsey makes essentially the same point when it divides the developing space economy into its “backbone” and its “reach.”

The backbone includes rockets, satellites, and ground infrastructure.

But the reach includes all the businesses that can eventually use that infrastructure to create products and services back here on Earth.

It’s the difference between investing in railroads and realizing railroads would also create Sears.

Or investing in internet infrastructure and realizing the same network would eventually produce Amazon, Google, Uber, Netflix, and thousands of other companies.

The infrastructure comes first. The truly enormous economic ecosystem comes afterward.

The Space Transportation Boom

That’s why I think investors need to look beyond rockets when considering the space economy.

Launch is critical because it’s the bottleneck being broken.

But breaking that bottleneck could unleash opportunity throughout the entire ecosystem.

There will be companies transporting payloads to orbit, companies building satellites, companies moving those satellites around once they’re there, companies servicing equipment in space, companies operating communications networks, companies processing satellite data, companies manufacturing products in microgravity, and companies building businesses we can barely conceptualize today.

The thing is, we don’t need to predict every one of them…

Investors in the 1860s didn’t need to foresee Walmart to understand the importance of connecting America.

Investors in the 1990s didn’t need to imagine artificial intelligence to understand the importance of connecting the world.

And investors today don’t need to know exactly what the trillion-dollar space company of 2040 will do.

We just need to recognize the pattern:

Build the transportation network. Lower the cost of accessing it. Increase its speed, capacity, and reliability…

And entrepreneurs will figure out what to put on it.

That process transformed America once with railroads, again with highways, and again with the internet. Now we’re watching it happen in space.

And history suggests that the biggest opportunities probably aren’t the ones we can already see…

They’re the ones that become possible once getting there is no longer the problem.

For most of the AI boom, investors have been obsessed with computing power…

Who makes the fastest chips? Who builds the biggest data centers? Who supplies the networking equipment connecting millions of processors together?

But an increasingly serious problem is emerging further down the infrastructure stack.

You can buy all the Nvidia chips you want and you can build a billion-dollar data center.

But none of it matters if you can’t turn the lights on.

And across America, that’s becoming a very real problem.

At least 75 U.S. data-center projects worth roughly $130 billion encountered local opposition during the first quarter of 2026 alone, according to Reuters. 

Concerns include electricity consumption, higher utility bills, water usage, noise, and the strain enormous computing facilities can place on local infrastructure.

And the backlash has become serious enough that some projects are being delayed, reconsidered, or stopped outright.

New York recently became the first state to impose a one-year moratorium on construction of large new data centers consuming 50 megawatts or more.

Texas — arguably America’s hottest data-center market — has temporarily halted approvals for new projects seeking connections to its power grid while state officials conduct an audit.

And the numbers help explain why…

Roughly 90% of the astonishing 474 gigawatts of proposed new electricity demand being reviewed in Texas comes from data centers. 

That’s more than five times the state’s current peak electrical load.

And it tells you that AI doesn’t just have a power problem…

It has a grid problem.

More Electricity Than the Grid Can Deliver

Data-center demand isn’t slowing down…

Goldman Sachs estimates electricity consumption from U.S. data centers could rise from approximately 31 gigawatts in 2025 to 66 gigawatts in 2027.

Wood Mackenzie sees U.S. data-center capacity reaching roughly 110 gigawatts by 2030, compared with approximately 24 gigawatts today.

That’s an extraordinary amount of new electricity demand arriving very quickly. And the problem is that America’s electrical infrastructure wasn’t designed for it…

Building generating capacity takes time. 

So does constructing substations, transmission lines, transformers, and all the other infrastructure necessary to move electricity from where it’s generated to where it’s consumed.

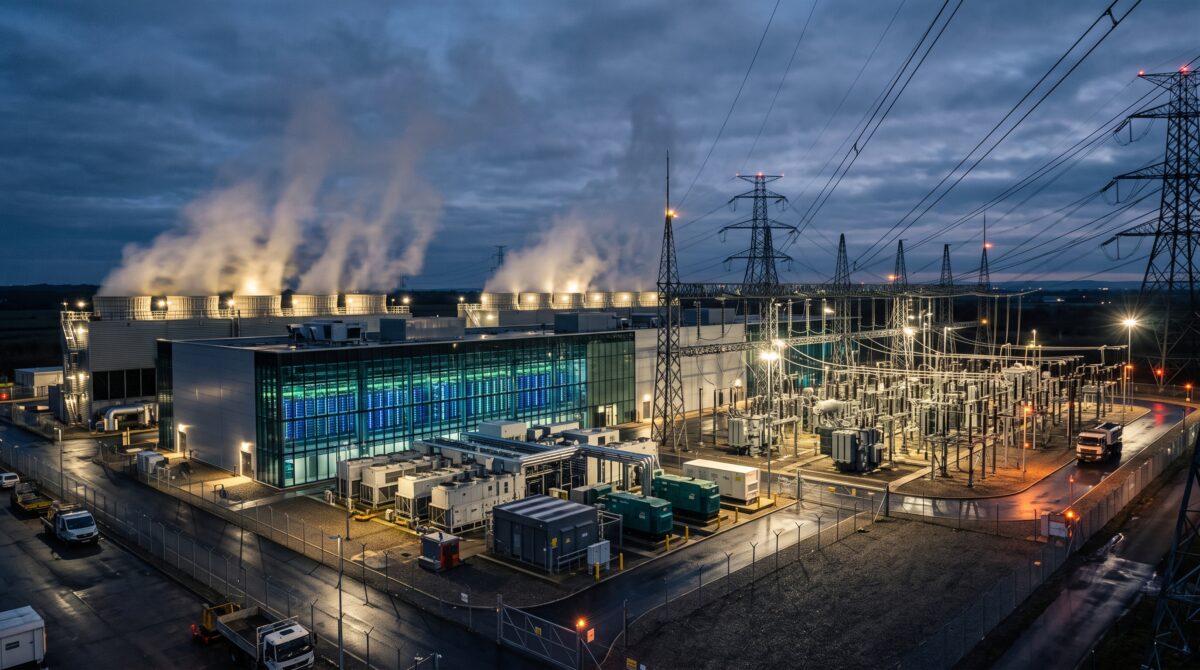
So, in many regions, developers can secure the land, financing, equipment, and customers for a data center long before they can secure the electricity necessary to operate it.

And that’s why a new phrase has started becoming increasingly important in the AI infrastructure business:

Time to power.

Investors are beginning to prioritize energy projects based not simply on what electricity costs, but how quickly that electricity can actually reach a new data center.

And that’s where things get interesting. Because perhaps the solution isn’t endlessly expanding the grid to accommodate data centers…

Perhaps data centers can start bringing their own fully-powered grid.

Bring Your Own Power Plant

That’s already where the industry appears to be heading…

PJM Interconnection, which operates America’s largest electrical grid, has considered requiring massive electricity consumers — primarily data centers — to either develop their own power supplies or accept arrangements allowing their consumption to be curtailed during periods of grid stress.

Think about what that means…

For decades, the basic infrastructure model was straightforward:

Build a factory, office building, hospital, or data center and plug it into the electrical grid.

But AI data centers consume electricity on an entirely different scale. That scale could eventually turn energy generation into part of the data center itself…

And one technology may be particularly well suited to doing it.

The Nuclear Battery

You’ve probably heard about small modular reactors, or SMRs. 

But there’s another category of advanced nuclear technology that’s considerably smaller, but potentially more lucrative…

They’re called microreactors.

The Department of Energy describes them as compact nuclear reactors small enough to potentially be transported by truck. 

And they’re being developed to supply reliable electricity to locations ranging from remote communities to military bases.

Now we can add AI data centers to that list…

You see, instead of building an enormous conventional nuclear power station, developers envision compact reactors that could be manufactured in factories and delivered where the electricity is needed.

So, a data-center campus could potentially operate several.

Need more computing capacity? Add more servers.

Need more electricity? Add more reactors.

And the result starts looking less like the traditional relationship between a power plant and an electricity customer and more like a giant nuclear-powered battery sitting beside the data center.

Except unlike traditional batteries, nuclear reactors can continuously generate power day and night.

There’s no waiting for the sun. There’s no dependence on wind.

And there’s far less dependence on an already overcrowded electrical grid.

That’s why the Department of Energy is taking the concept seriously.

So seriously that it’s already provided support for projects exploring microreactors and sites capable of hosting nuclear-powered data centers.

And that brings us to one particularly interesting design…

Meet Morpheus

A company called Nuclea Energy is developing a microreactor called Morpheus.

And one of the markets Nuclea specifically identifies for the technology is AI and data centers.

Morpheus is designed around a compact lead-cooled nuclear architecture intended to operate in locations where conventional energy infrastructure can be difficult, expensive, or impossible to build.

That original mission included remote communities, mining operations, military installations, and extreme environments.

But suddenly the same characteristics look remarkably well suited to America’s AI infrastructure problem…

A data-center operator doesn’t necessarily need another gigantic regional power plant.

It needs reliable electricity right beside the computers.

Microreactors offer the possibility of distributed nuclear generation capable of operating continuously with a very small physical footprint.

They’re also quiet, low-carbon, and capable of operating for extended periods without the constant fuel deliveries associated with diesel or natural-gas backup generation.

In other words, something resembling a long-duration nuclear battery.

Morpheus isn’t commercially deployed yet, and that’s an important distinction. 

Advanced reactors still face licensing, manufacturing, financing, deployment, and first-of-a-kind cost challenges. 

And even the Department of Energy warns that new nuclear designs will take time to deploy and early reactors can be expensive.

But those hurdles don’t diminish the problem they’re attempting to solve. They simply help explain why solving it could become so valuable.

The Picks-and-Shovels Opportunity Is Changing

For the past several years, investors have made fortunes betting on the infrastructure behind AI…

Semiconductors, servers, networking equipment, cooling equipment, data centers, utilities, transformers, and electrical contractors have all benefited.

But infrastructure bottlenecks evolve.

First, we didn’t have enough chips. Then we didn’t have enough data centers…

Now, increasingly we don’t have enough accessible power.

And that’s why the next stage of the AI infrastructure boom may produce a new class of winners…

Companies capable of allowing data centers to generate electricity themselves.

That’s bigger than simply selling another megawatt of power because it could remove one of the biggest constraints preventing billions of dollars of computing infrastructure from being built.

Remember those 75 projects worth $130 billion that encountered resistance in just three months?

Every delayed data center makes a solution that can reduce dependence on local power infrastructure a little more valuable.

Every overloaded transmission line makes distributed generation more attractive.

Every community worried that an enormous AI facility will raise residents’ electricity bills strengthens the argument for making that facility supply more of its own power.

And every additional AI model requiring another warehouse filled with processors increases the urgency.

The AI revolution still needs chips. It still needs servers. It still needs data centers…

But increasingly, the most valuable piece of equipment on tomorrow’s AI campus might not be sitting inside the data center at all.

It might be the little nuclear reactor sitting outside it.

Mention the space economy, and most investors immediately picture missiles, surveillance satellites, military communications, and governments competing for control of the ultimate high ground.

That reaction is understandable because space has become central to modern warfare. 

Satellites guide weapons, track troop movements, detect missile launches, transmit intelligence, and keep military units connected across continents. 

And as governments increase defense spending and build new constellations, the military side of the space economy is becoming more visible by the year.

But visibility isn’t the same thing as size…

You see, the commercial space economy is already considerably larger than the government and military market most people associate with the industry. 

And as launch costs fall, satellite manufacturing accelerates, and space-based services spread into nearly every major industry, that gap is likely to become much wider.

Because space may be the next battlefield. But it’s also becoming the next layer of civilian infrastructure.

A Commercial Economy Hiding in Plain Sight

The global space economy reached approximately $686 billion in 2025, representing roughly 12% growth from the previous year. 

And commercial activity accounts for the overwhelming majority of that market… 

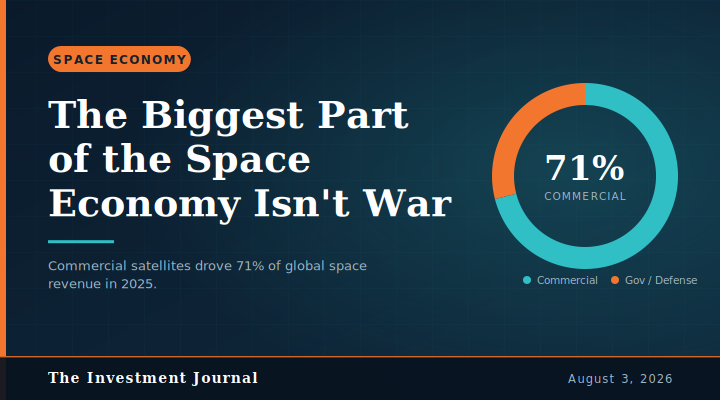
In fact, one industry estimate found that commercial satellite businesses alone generated 71% of worldwide space-related revenue during 2025.

That means the space economy is no longer a collection of government programs…

It’s already a commercial marketplace.

Most people simply don’t recognize it because they interact with space infrastructure without thinking about it. 

They use Google Maps to find a restaurant, check the Weather app before leaving home, follow an Amazon shipment across the country, make a credit card purchase, watch live television, or place a phone call from an isolated area.

Many people don’t realize it, but all of those activities depend, directly or indirectly, on satellites…

Space-based infrastructure helps farmers decide where to irrigate and it helps airlines choose more efficient routes. 

It helps energy companies inspect pipelines, governments respond to natural disasters, insurance companies estimate property damage, and shipping companies track vessels across the oceans.

But the customer usually isn’t buying “space.” 

The customer is buying connectivity, navigation, imagery, data, efficiency, or greater visibility into something happening on Earth.

And that distinction is important because it reveals where the industry is heading…

The largest space companies of the future may not make most of their money selling rockets or satellites. 

They may make it by selling ordinary businesses better information and better services that happen to originate hundreds of miles above the planet.

From Hardware Industry to Information Industry

The first phase of the commercial space economy was largely about building the physical infrastructure…

Companies manufactured satellites. Rocket operators launched them. Ground stations communicated with them. And telecommunications providers sold access to their networks.

And those industries will continue growing, particularly as the number of satellites increases. 

A record 4,434 satellites were deployed in 2025, 65% more than in 2024, while the total number of active satellites surpassed 14,000 in early 2026.

But the more consequential shift is happening one layer above the hardware…

You see, as satellites become cheaper, smaller, more capable, and more numerous, the data they produce becomes easier to collect and more valuable to process. 

Artificial intelligence can examine millions of images, signals, weather observations, and geographic measurements far faster than human analysts ever could.

And that transforms satellites from specialized pieces of aerospace equipment into components of a global information network…

An Earth-observation company, for example, doesn’t merely sell pictures of the planet. 

It can help a mining company identify geological features, tell a retailer how many cars are parked outside competing stores, estimate agricultural production, detect methane leaks, track illegal fishing, or measure activity at ports and factories.

And a navigation satellite doesn’t merely tell someone where they are. 

Its timing signal helps synchronize telecommunications systems, electrical grids, bank transactions, and data networks.

A communications satellite doesn’t merely beam television programming, either… 

It can connect aircraft, ships, farms, mines, factories, autonomous vehicles, emergency crews, and communities located far beyond the reach of terrestrial broadband.

The hardware enables the service. But the service is where the much larger economy develops.

The Road to $1.8 Trillion

The World Economic Forum and McKinsey estimate that the global space economy could reach $1.8 trillion by 2035, up from approximately $630 billion in 2023. 

And their forecast suggests that much of the expansion will come not just from traditional space businesses, but from “reach applications.”

Those are industries that use space technology to create products, services, and revenue here on Earth.

That could include agriculture, transportation, telecommunications, insurance, financial services, mining, energy, construction, logistics, climate monitoring, and consumer electronics.

In other words, the space economy is likely to grow the same way the internet economy grew…

At first, investors focused on the companies building computers, laying fiber-optic cable, and operating networks. 

Eventually, however, the largest opportunities emerged among businesses that used that infrastructure to reinvent advertising, retail, entertainment, banking, transportation, and communications.

Space is likely to follow a similar progression…

Rocket companies and satellite manufacturers are creating the underlying network. And the next generation of companies will build applications on top of it.

Now, some of those applications are already obvious… 

Satellite broadband can connect populations that terrestrial networks can’t economically reach. 

Direct-to-device networks could eventually allow ordinary phones to communicate with satellites when cellular service disappears. 

Amazon, for example, has proposed a constellation of more than 5,000 satellites designed to support global voice, messaging, data, and emergency communications.

And other applications will emerge as the infrastructure improves…

Continuous Earth observation could give businesses a near-real-time view of global economic activity. 

Satellite-connected machines could operate in deserts, oceans, forests, and agricultural regions where terrestrial communications remain unreliable. 

Space-based sensors could detect wildfires, floods, crop disease, maritime pollution, and infrastructure failures earlier than existing systems.

You see, the value won’t come from simply placing more objects in orbit… 

It’ll come from turning the information those objects gather into something people and businesses are willing to pay for.

Launch Is Becoming Transportation

But the thing is that every part of this growth trajectory depends on access to orbit.

And historically, launching a satellite requires a large rocket, a government-sized budget, and years of planning. 

That has made space available primarily to nations, defense contractors, telecommunications giants, and a small number of extremely well-funded organizations.

But that barrier is falling, thanks to innovative new companies and ideas…

The satellite industry completed a record 296 launches in 2025, and U.S. regulators approved 204 commercial space operations during the year. 

And the growing launch cadence reflects a market that is gradually moving away from one-off missions and toward something resembling scheduled transportation.

But that small change could be as important as any individual satellite technology…

Because industries expand when transportation becomes cheaper, faster, and more dependable. 

Railroads opened continents. Container ships globalized manufacturing. Commercial aviation connected markets that once took weeks to reach.

Reliable launch services will do something similar for orbit…

More frequent launches allow companies to deploy smaller constellations, replace damaged satellites, update technology faster, and design missions around business requirements rather than rocket availability. 

They also make space accessible to universities, startups, research institutions, regional governments, and companies that could never have funded an entire launch themselves.

And different missions will require different launch systems… 

Large rockets will carry entire constellations and heavy infrastructure. 

Smaller rockets can provide dedicated delivery. 

Air-launched systems may offer speed, flexible launch locations, and the ability to place smaller payloads into specific orbits without waiting for a traditional launch schedule.

You see, the opportunity isn’t necessarily to replace the largest rockets. It’s to fill the growing transportation gaps around them.

An Economy That Eventually Moves Off Earth

Most commercial space revenue today is generated by services delivered back to Earth. And that will remain the industry’s economic foundation for years.

But it probably won’t remain the limit…

Once transportation becomes frequent enough and orbit contains enough infrastructure, companies can begin conducting more business in space itself.

Private space stations could host scientific research, pharmaceutical development, tourism, manufacturing, and astronaut training. 

Microgravity may enable materials, biological products, and industrial processes that are difficult or impossible to produce under Earth’s gravity.

Satellites will require maintenance, refueling, inspection, and eventual removal. 

That could create markets for orbital servicing vehicles, fuel depots, debris-removal systems, repair platforms, and space-based logistics.

Lunar activity could eventually generate demand for communications, navigation, energy, transportation, construction, and resource extraction around the Moon. 

Each of those markets would require an entire supporting ecosystem.

Now, that’s not to say we should assume every futuristic business plan will work. Space remains expensive, technically difficult, heavily regulated, and unforgiving of mistakes.

But that was also true of commercial aviation, offshore energy, semiconductors, and the early internet.

The important point isn’t that every proposed space industry will become viable. 

It’s that the basic ingredients of a much larger commercial economy are falling into place…

Lower launch costs, mass-produced satellites, private capital, improving communications, artificial intelligence, reusable hardware, and a rapidly expanding customer base.

More Main Street Than Star Wars

Military spending will remain an important part of the space economy. 

And in some areas, government contracts will help finance technologies that later find civilian customers…

Communications, navigation, remote sensing, and launch capabilities have always moved back and forth between public and private markets.

But defense isn’t the entire space story, and it may eventually become a relatively small part of it.

The larger opportunity is a world in which space infrastructure becomes embedded in ordinary economic activity.

It’ll help farmers grow more food, communications companies reach more customers, manufacturers manage their supply chains, insurers better understand risk, ships navigate more efficiently, emergency crews respond faster, and consumers stay connected almost anywhere on Earth.

And later, it may support factories, research laboratories, hotels, fuel depots, and transportation networks operating beyond the planet.

That is how the space economy ultimately becomes far larger than the military market that captures most of today’s attention.

The rockets may be the most dramatic part and the defense contracts may generate the biggest headlines…

But the enduring economic opportunity will be built from thousands of civilian services quietly becoming faster, cheaper, safer, and more capable because they’ve gained access to space.

That’s why the future of the space economy won’t look only like a missile warning system or a science-fiction battle.

It’ll look like infrastructure. And eventually, it’ll be almost everywhere.